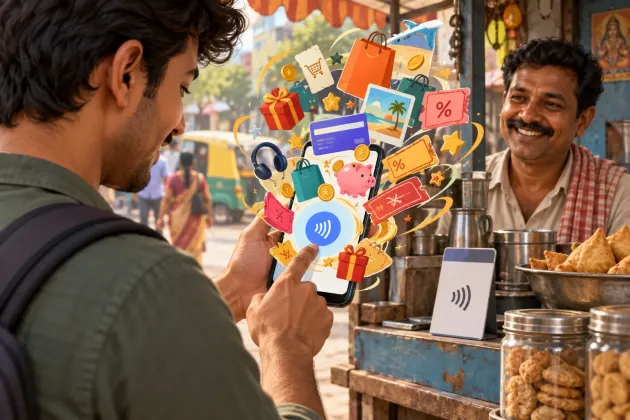
Your UPI app does not want to remain a payment button. It wants to be where you browse, borrow, insure, invest and return for the next reward.
That is not a free bonus. It is a business model wrapped around a tool you reach for whenever you pay. The awkward part is that the app feels too essential to challenge. You may ignore a shopping app for a week; you still need to scan the tea stall's QR code.
The answer is not to hunt for a mythical app with no commercial motive. It is to decide what your payment app is allowed to do on your phone, then make everything else inconvenient enough that you stop entering by accident.
The payment rail is not the shopping aisle
Newer UPI apps are using rewards to turn frequent payment users into customers for credit, commerce and other financial products, Mint reported in June 2026. That sentence explains most of the clutter. The payment is the reliable habit; the reward, loan tile or shopping offer is the door into a business that can earn more.
The mechanics are not subtle. Moneycontrol reported in 2025 that Google Pay's rewards included scratch cards, cashback and promotional games. The same report said PhonePe offered cashback and SuperCoins that could be exchanged for offers and gift vouchers. These features may occasionally save you money, but they also give you a reason to stay after the payment is finished.
Do not confuse the app with the payment system underneath it. Business Standard described Indian wallet apps in June 2026 as front-ends to UPI operating on a single interoperable rail. In plain English: you are choosing an interface around UPI, not swearing lifelong loyalty to one colourful home screen.
The commercial expansion is real. Business Standard also described PhonePe and Paytm as financial super apps combining payments with credit, insurance, investments and commerce. Once all of that sits beside Scan and Pay, opening the app is no longer a neutral act. You entered to pay the sabzi vendor; the app gets a chance to pitch something else before you leave.
Decide what the app is allowed to be
Give your default UPI app a narrow job description: scan, pay, receive money, check a failed transaction and leave. Write that rule in your head before you change any setting. If a tile does not help with that job, treat it as an advertisement even when the app labels it a benefit.
Start with the home screen. Keep your default payment app where your thumb can reach it. Move shopping, investment, credit and rewards apps into a folder on another screen. This does not block anything. It inserts a small pause between an impulse and an action, which is exactly what a crowded payment app tries to remove.
Now open your phone's notification settings, not the UPI app's promotional page. Disable marketing, reward, offer and game alerts wherever the system gives you separate controls. Keep transaction and security alerts. If the app bundles useful alerts with sales messages, leave them on but stop acting on anything that does not concern a payment you already made.
Finally, remove shortcuts and widgets that lead into rewards or shopping. Do not spend an evening trying to redesign the app itself; I have lost enough time arranging folders to know that tidying can become its own form of avoidance. Your goal is a faster exit, not a beautiful dashboard.
Give each money app one job
One app should be your default for everyday UPI payments. A second can be a backup for the day your default refuses to cooperate. Every other payment app needs a specific reason to remain installed. “There might be a coupon” is not a reason; it is an invitation to maintain several noisy accounts.
Your bank app is for banking. Your shopping app is for purchases you planned before opening it. Your investment app is for investments you understand and intended to make. When a UPI app offers all three, do not reward the convenience by letting it collapse those decisions into one tap.
If your current interface makes that separation impossible, try a quieter alternative before you surrender. Moneycontrol described BHIM in 2025 as simple, fast and ad-free, while noting that it did not consistently offer cashback or vouchers. Check the current version for yourself because interfaces change, but use the right test: can you reach payment and transaction history without walking through a bazaar?
Keep the backup off your first home screen. A backup is a spare key, not a second front door. Open it occasionally to make sure your account access still works, then close it. Do not duplicate every bill, mandate and reward programme across both apps unless you have a clear operational need.
This division also makes problems easier to understand. When a payment fails, you know which app to check. When a purchase tempts you, you know it belongs in the shopping decision, not the payment decision. Simplicity is less about deleting features than about refusing to let one screen set the agenda for your money.
Put rewards on a leash
A reward is useful only when it discounts something you had already decided to buy. Reverse that order and the reward becomes a shopping prompt. The coupon is not saving you money if it creates the purchase.
Use a hard stop after every successful payment. Confirm the recipient and amount, wait for the success screen, then close the app. Do not scratch, spin, collect or “just check” what unlocked. You can review genuine cashback later, when you are not standing at a counter with people waiting behind you.
Create one boring rule for coupons: compare the final cost with the price you would otherwise pay, including delivery, minimum order and the extra item needed to qualify. If you would not buy at the undiscounted moment, the offer has failed your test. An expiry timer changes nothing about whether you need the product.
Treat credit prompts more strictly than shopping coupons. A payment app knows you arrived to move money, so a credit tile can feel like part of the same routine. It is not. Close the app and evaluate borrowing separately, with the repayment amount, fees and purpose in front of you. Convenience at the point of payment is not a substitute for a credit decision.
Rewards do not need a total ban. If you enjoy them, schedule a deliberate review when you have time to read the conditions. Redeem only what fits an existing bill or purchase. The moment you start changing where, when or how much you spend to complete a reward task, the app is directing your behaviour.
Reset without breaking the useful parts
Do not begin by deleting your only working payment app outside a shop. Begin at home, with your bank details and mobile connection available. Note which app handles your recurring mandates, pending disputes and important payment history. The aim is to reduce clutter without losing track of obligations.
Then make the smallest effective changes. Silence promotions. Move the icon. Remove redundant payment apps. Stop opening the rewards section. Use the stripped-down routine for ordinary payments and notice what you actually miss. You may discover that the feature you thought was essential was merely bright.
If you switch default apps, keep the old one long enough to settle pending issues and verify mandates. Do not assume that uninstalling an interface cancels an obligation. Check each recurring payment with the service that charges you, and keep records of anything disputed. Boring administration now is cheaper than rediscovering an forgotten mandate later.
Ask family members before simplifying a shared routine. The app on your phone may also be the place where a parent expects help finding a bill or checking whether money arrived. Preserve the path they understand, then remove only the clutter that does not support it. A clean setup that confuses the household is not simple.
Run this reset again whenever the home screen changes dramatically. New tiles often arrive quietly after an update. You do not owe each one a trial. Your payment app is infrastructure in your life, not a weekend destination.
What to actually do
- Choose one default UPI app and give every other payment app a written reason to stay.
- Turn off promotional alerts while preserving transaction and security notifications.
- Move shopping, rewards, credit and investment shortcuts away from your payment path.
- Close the app as soon as you confirm a successful payment.
- Redeem only rewards that fit a purchase or bill you had already planned.